The independent data source for semi-liquid private markets funds in Europe
We read prospectuses, key information documents and reports, collate what they say and make it comparable. Privately funded, with no mandate from any provider and no rankings.
- 140
- funds, ELTIFs and evergreen structures
- 91
- providers
- 1,614
- share classes, each recorded individually
- 32
- countries in the access check
Product data as at 16 Oct 2026 · distribution and access data as at 5 Oct 2026 · every value carries its source
The terms are in the prospectus. The comparison was nowhere to be found.
With ELTIF 2.0 and the evergreen funds of the large managers, private equity, private credit, infrastructure and real estate are now open to private investors in Europe as well. That is a good development for an ecosystem that was long reserved for institutions.
There is a catch. What a fund really costs, when you get your money back and what happens when many investors want to sell at the same time is buried somewhere around page 80 of a prospectus, worded differently by every provider and expressed in different units. Comparing two funds means reading two prospectuses.
semiliquid.info translates these terms into the same fields for every fund: redemption windows, notice periods, gates, lock-ups, costs, minimum investment and access by country. Every value carries its source and its date. That is all we do, but we do it thoroughly.
We do not judge whether a fund is good. We show what the prospectus says and make it comparable.
Editorial principle
A source for every value
Prospectus, PRIIPs KID or report, with the document date. Where there is no source, the field stays empty rather than estimated.
The same criteria for all
Inclusion follows documented rules. No provider is favoured, and none is left out for not asking.
No money from providers
No commissions, no advertising, no paid placements. How you can verify this is set out under Transparency.
Corrections welcome
We check readers’ reports against the original document and correct promptly.
A fund selector who keeps reading after hours
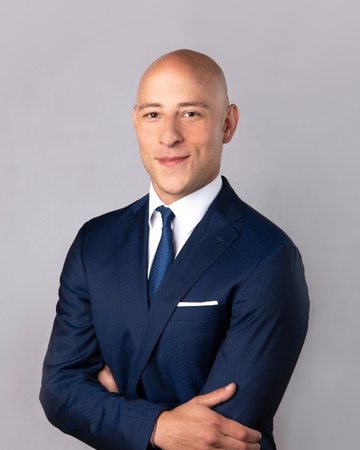
Niko Hatziiosifidis
Publisher and editor
Senior Portfolio Manager and Head of Fund Selection at a renowned Swiss private bank. In his day job he selects funds across all asset classes for client portfolios, which means reading prospectuses. That led to the idea of doing the same systematically and publicly for semi-liquid funds.
- Education
- Industrial engineering and management, bachelor’s and master’s degrees, TU Darmstadt and Karlsruhe Institute of Technology
- Focus
- Fund selection, fixed income, multi-asset, private markets
- Contact
- contact@semiliquid.info
Conflict of interest, stated openly
Semi-liquid funds are not an investment focus at his employer. The site is a private project, produced without any mandate, resources or data from the employer, and does not reflect the bank’s views. More under Transparency.
What this site is not
No investment advice, no recommendations, no distribution. Whether a fund suits you is your decision, based on the original documents and together with your adviser where appropriate.
Since when
Public since August 2026 and extended continually since: access check for 32 countries, peer group indices, liquidity report, gating monitor.
From prospectus to comparable figure
Four steps, in this order, for each of the 140 funds. The first is the most laborious.
Sourcing
Prospectus, PRIIPs KID, annual and semi-annual reports, directly from the provider, from fund registers or data portals. For each fund, every available document, across all share classes.
Prospectus · KID · reportsRecording
Every field gets its source and document date. Notice periods are converted into calendar days, costs are put on a PRIIPs KID basis, share classes are kept separately.
Provenance for every valueChecking
Plausibility runs across the whole dataset, spot checks against the original document. Open points stay marked as open rather than being filled with a plausible value.
Audit logPublishing and updating
Product data continuously, net asset values monthly, access data by matching against ESMA and national registers. Readers’ reports are incorporated after checking against the original document.
Data date in every footer
Methodology at a glance
Three methods and one inclusion rule underpin the site. All of them are disclosed, with the details on their own pages.
Liquidity score
One number from 0 to 100 for one question: how many days pass between the redemption request and the cash according to the prospectus?
- 7 days
- 100 points
- 3 years
- 0 points
- Doubling
- −13.7 points
- Two views
- from today · existing holding
Peer group indices
One equally weighted total return index per segment, built from the net asset values of the funds in this database, base 100, in euros.
- Segments
- PE · PC · Infra · Real estate
- Frequency
- monthly · quarterly
- Since
- August 2026, back-calculated
- Weighting
- equal, per period
Access check
Who may subscribe in which country? Derived from ESMA and national registers, per share class, for the EEA states, Switzerland and the United Kingdom.
- Countries
- 32
- Level
- share class (ISIN)
- When in doubt
- rather no than yes
- As at
- 5 Oct 2026
Inclusion criteria
- Semi-liquid private markets funds accessible in Europe, with regular redemptions, mainly unlisted assets and a publicly available prospectus or key information document
- Closed-ended funds without redemption, vehicles without public documents, purely institutional structures with no share class accessible to retail investors
Whether a fund is actually accessible in your country is answered by the access check. We cover it either way.
Liquidity score: the components in detail
| Component | What goes in | Effect |
|---|---|---|
| Waiting time | Redemption frequency, notice period, NAV lag and payout period, in calendar days, with a bank-holiday calendar | 7 days = 100 points, 3 years = 0 points; every doubling of the waiting time costs 13.7 points |
| Entitlement | Redemption right, repurchase offer or board discretion | Factor 1.0 · 0.8 · 0.7 |
| Certain exit costs | Permanent discount; time-limited fee if the earliest exit still falls within the fee period | −7 points per percentage point |
| Lock-up | View “from today”: lock-up plus the chain of deadlines · view “existing holding”: the chain of deadlines alone | Two values per fund |
| Ongoing scaling back | Documented fulfilment ratio q of an active gate | Waiting time times 1/q |
| Beside the number | Gate profile A–D, transparency A–D, status, confidence A–C. Whatever depends on the behaviour of other investors sits beside the number as a letter, not inside the value | No points |
Peer group indices: the parameters in detail
| Index family | semiliquid.info peer group indices |
| Segments | Private equity, private credit, infrastructure, real estate |
| Return type | Total return, net of the ongoing charges of the share class used |
| Weighting | Equally weighted, reset at the start of each period |
| Index currency | Euro, unhedged; ECB reference rates at month end |
| Base | 100, per segment the period preceding the first qualifying observation |
| Calculation | Monthly and quarterly; first published in August 2026, history prior to that back-calculated |
| Data basis | Net asset values from provider documents, price feeds and market data vendors |
| Update cycle | Monthly, as fund valuations are received |
Eligibility, the treatment of unvalued periods and of distributions, the revision policy and the known limitations (back-calculation, survivorship bias, valuation smoothing) are set out in full in the index methodology.
Questions we are asked
Is semiliquid.info investment advice?
No. The site presents prospectus information in comparable form and does not assess whether a fund suits you. The liquidity score measures time and certainty until payout, not the quality of a fund. Decisions are yours to make on the basis of the original documents, together with your adviser where appropriate.
How up to date is the data?
Every value carries the date of the document it comes from. We update product data continuously, net asset values monthly and access data by matching against the registers. The overall data date is shown in the footer of every page. The provider’s current document always takes precedence.
Why is a particular fund missing?
Either it does not meet the inclusion criteria (closed-ended, no public documents, institutional only), or we have not yet added it. A note with the fund name or ISIN to contact@semiliquid.info is enough. Inclusion is free of charge and follows the same rules as for every other fund.
How is the site funded?
Privately. There are no commissions, no advertising, no paid placements, no data licences and no subscription. Should that change, it will be stated beforehand under Transparency, with the source, the order of magnitude and what it affects.
May I use the figures and charts?
Aggregate figures, charts and reports are published under CC BY 4.0 and are free to use with the credit “semiliquid.info”. Fund-level information comes from the providers’ documents; please cite the original document there. Files and citation format are under Use our data, material for journalists under Press.
Is there a newsletter?
A change alert: we write when something in the market changes, such as a new authorisation, a changed redemption window, a gate, a change in costs or a new fund. There is no fixed schedule. You can sign up on the home page.
Get in touch
One address for everything. We reply personally.
We check reports of data errors against the original document. The fund name or ISIN is enough; the page reference helps.
Feedback and suggestions
What is missing, what is confusing, what you would like to see done differently. Every message is read.
An error in the data?
If an entry does not match the current prospectus, send us the fund name or ISIN. We check against the original document and correct it promptly.
Providers and media
Is your fund missing or has it changed? Inclusion follows the documented criteria and is free of charge. Material for journalists is available under Press.